Okay, real talk. If you've ever worked loan files, you know that specific kind of exhaustion that comes from chasing a borrower for the third time about a bank statement they swear they already sent. Or fixing a typo on a 1003 at 6 pm on a Friday. Or getting a "just one more document" email from underwriting when you thought the file was done. Nobody dreams of doing that forever.
So it's not shocking that lenders have spent the last couple of years asking the same thing. Does this actually have to happen in-house? By 2026, a lot of them have landed on nope.
Loan processing outsourcing isn't some fringe move anymore. It's just how a lot of shops run now. Not because lenders got lazy or stopped caring; honestly, it's the opposite. Compliance keeps getting stricter, borrowers keep getting less patient, margins keep getting thinner. White-knuckling every step in-house doesn't feel safe anymore. It feels risky.
The Money Part
Origination costs went up a lot. Add up salary, benefits, training, and the constant churn of processors quitting for a two-dollar raise elsewhere, and in-house starts looking like what you'd pay a specialized team to do it right. Nonbank lenders especially have moved toward full-service outsourcing fast.
What "End-to-End" Actually Means Now
A few years back, "outsourcing" usually meant one thing got farmed out, maybe data entry or document indexing. Not really the model anymore.
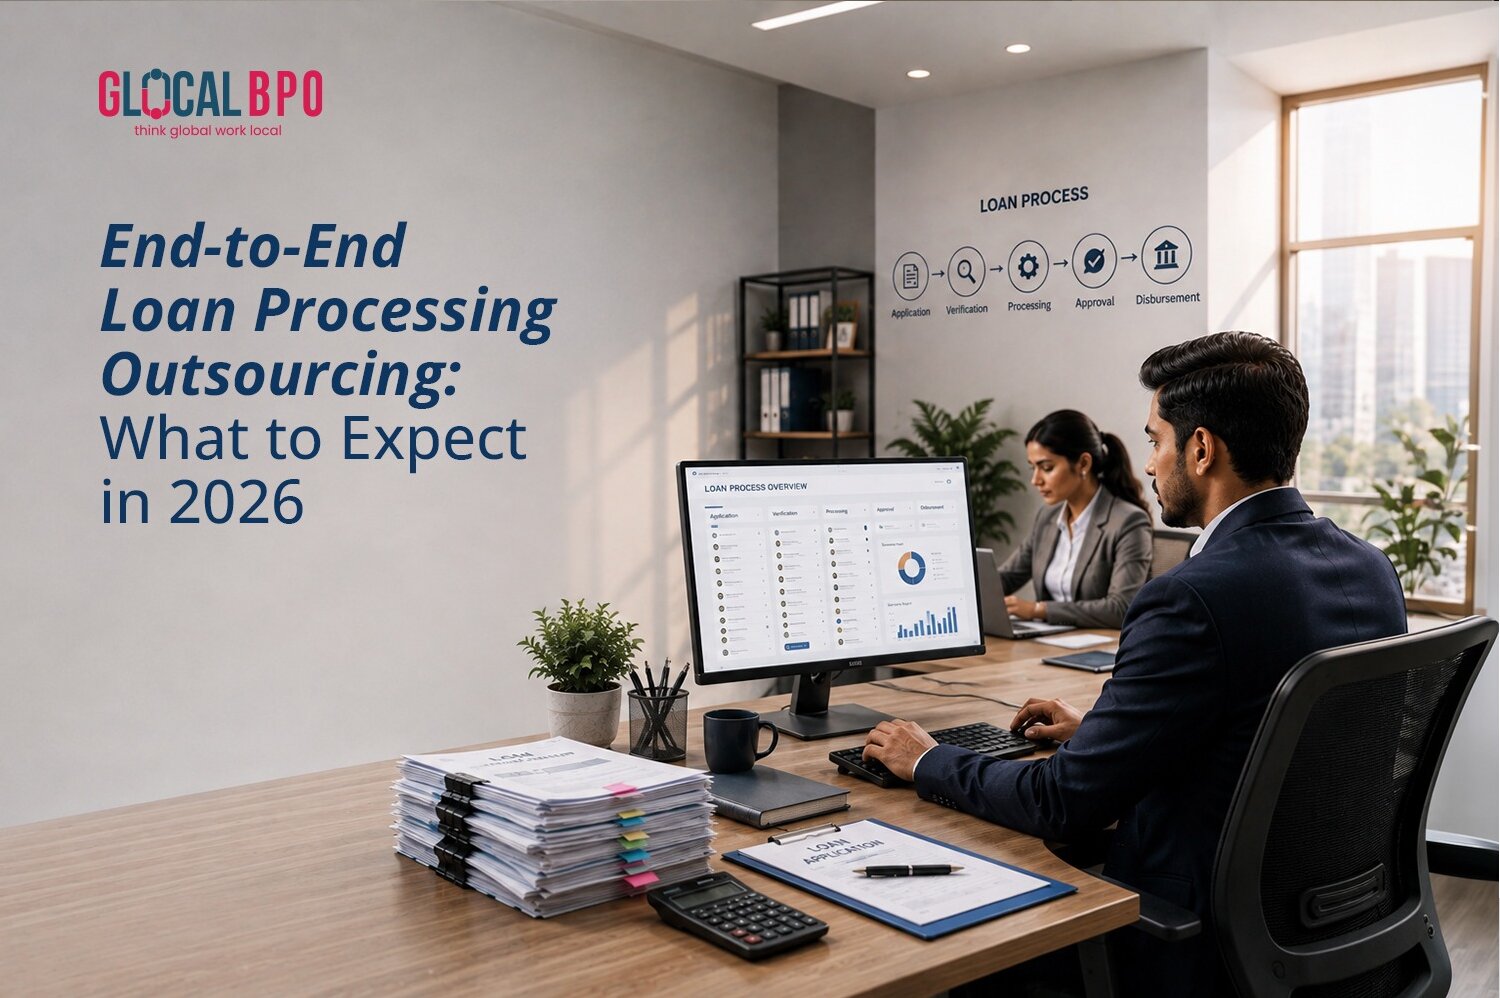
A real end-to-end partner just handles the whole thing now. That's pre-qualification, sure, but also the document chasing, making sure underwriting gets a file that's clean instead of half a mess, checking it against Truth in Lending and fair lending rules so nothing slips, and staying in the picture past closing into servicing. It's not one job anymore; it's your whole back office living somewhere else.
And once a partner can pull that off, the way you think about them changes on its own. They stop being "the outsourced people" and start being your extended team. The one that happens to sit in a different building, maybe a different country, doing real work on real files every day. That's the bigger shift here, more than any software anyone's rolled out.
Turns Out Time Zones Are Kind of a Cheat Code
Outsourcing doesn't just save money; it often makes things faster, for a fairly boring reason. A file submitted at 6 pm Eastern doesn't sit there until someone rolls in at 9 am. With teams on the other side of the clock, that file gets worked overnight and lands back in your queue before you've poured coffee. Lenders are leaning into this and closing loans noticeably faster, not from cutting corners, just because the work never stops.
AI's Job Is to Help, Not Take Over
You've probably noticed everyone slapping "AI" onto everything in lending right now. The partners doing well aren't promising a robot will underwrite loans while everyone goes home early. They're using automation for the assistive stuff, pulling data, sorting documents, catching obvious inconsistencies, so humans can focus on calls that need judgment. A real person still looks at the file before it moves forward.
Regulators Aren't Loosening Up, So Don't Expect Outsourcing To Either
If you're hoping outsourcing means fewer compliance headaches because someone else deals with it now, that's not how this works. Regulators are watching borrower protection more closely than they have in a while: disclosure language, servicing complaints, all of it. One messed up file isn't just an annoyed customer anymore; it can turn into a formal complaint, and those turn into legal trouble fast.
That's exactly why people are pickier about who they trust to outsource loan processing services to. It's not just "can you do this cheap." It's "can you do this cheap and prove, whenever asked, that every file meets Truth in Lending, fair lending, and whatever state rules apply." If a partner can't answer that with a straight face, they're not a partner; they're a risk with a logo on it.
Commercial Loans Are Finally Getting Their Turn
For years, most outsourcing talk was about residential mortgages, mostly because that's where the volume was. But 2026 feels like the year commercial loan processing outsourcing stops being the afterthought. Commercial files are a different beast: multiple guarantors, full business financials, covenants to track long after closing, lawyers on top of underwriters. Lenders who kept this in-house because it felt too complicated to hand off are finding that complexity is exactly why specialized teams earn their fee. A team processing commercial files all day catches what a generalist would miss.
So, Should You Actually Do This?
Outsourcing isn't magic, and it's not risk-free. You're trusting someone else with sensitive borrower info and your reputation, earned through real security practices, not a nice slide deck.
Done right, though, it's hard to argue against. Lower fixed costs, faster turnaround, fewer compliance scares, and loan officers spending their time building relationships instead of playing document whack-a-mole all day.
2026 isn't really the year loan processing outsourcing "arrived." It's the year it stopped being optional if you want to compete on cost, speed, and compliance at once. The lenders pulling ahead aren't the ones with the shiniest software. They're the ones who found a partner that treats every file like it matters.
If your team's still buried in the manual side of this, it's worth asking what everyone else already answered. What would change if you didn't have to do it alone?
Glocal BPO helps lenders handle every stage of the loan lifecycle, from pre-qualification through closing, without cutting corners on compliance. Get in touch so we can call it in.